


Baidu Stock Forecast 2026: Why Wall Street Misreads Apollo and Ernie
Baidu trades at a steep discount despite dominating China's robotaxi rollouts and enterprise AI. Here is what analyst consensus misses about BIDU in late 2026.
8 min read

TL;DR Trading below 9x forward earnings despite profitable autonomous robotaxi deployments and rising enterprise AI software margins, Baidu presents an extreme valuation disconnect that institutional consensus is only now beginning to revise upward.
For three consecutive years, western equity analysts have treated Baidu (NasdaqGS: BIDU) as an uncomfortable riddle. To Wall Street, the Beijing-based tech giant is forever trapped in a penalty box formed by Chinese macroeconomic deceleration, regulatory caution, and fierce domestic competition from ByteDance and Tencent.
Yet as the final quarter of 2026 gets underway, the financial arithmetic surrounding BIDU is decoupling from that familiar narrative.
While mega-cap American cloud and AI infrastructure operators trade at forward price-to-earnings multiples between 28x and 35x, Baidu continues to hover around an austere 8.8x forward consensus earnings. That multiple implies a company in structural decline. But Baidu’s underlying business shows something entirely different: Apollo Go has reached operational cash-flow breakeven across key tier-one metropolitan zones, while the company’s Ernie foundational models have quietly captured the largest share of domestic enterprise generative AI workloads.
The question for investors in late 2026 is no longer whether Baidu can reinvent itself beyond search advertising. It is whether the equity market can accurately value an operational transformation that traditional discounted cash flow models have comprehensively ignored.
1. The Disconnect: What Consensus Models Are Getting Wrong
When looking across institutional equity research published over the past month, median 12-month price targets for Baidu’s American Depositary Receipts (ADRs) cluster around $132, implying roughly 38% upside from current trading ranges near $95. Yet that median conceals a widening ideological split among major brokerages.
On one end of the spectrum, conservative global desks maintain targets as low as $88, heavily discounting any revenue generated outside legacy advertising. On the other end, regional technology analysts covering mainland infrastructure see fair value north of $165, driven by accelerating AI cloud uptake and third-party platform licensing.
| Scenario | 12-Month Target | 2027e Forward P/E | Core Thesis Driver |
|---|---|---|---|
| Bear Case | $82.00 | 7.5x | Persistent ad slump; margin compression from localized AI chip migration |
| Base Case | $132.00 | 11.0x | Modest recovery in enterprise IT; Apollo Go breaks even nationwide |
| Bull Case | $174.00 | 14.5x | Cloud margins exceed 24%; monetization of autonomous vehicle licensing |
The core flaw in most consensus models stems from treating Baidu’s capital expenditure on artificial intelligence as speculative, long-tail R&D rather than productive commercial capacity. According to Baidu’s required disclosures with the U.S. Securities and Exchange Commission, the company has steadily redirected its capital allocation away from traditional content acquisition and consumer traffic acquisition costs, reallocating those billions directly into self-developed cluster networking and specialized data centers.
Where early AI investments dragged on operating margins between 2022 and 2024, those assets are now yielding recurring, high-margin software revenue that Wall Street’s top-down macroeconomic screeners routinely blend into generic “online marketing services.”
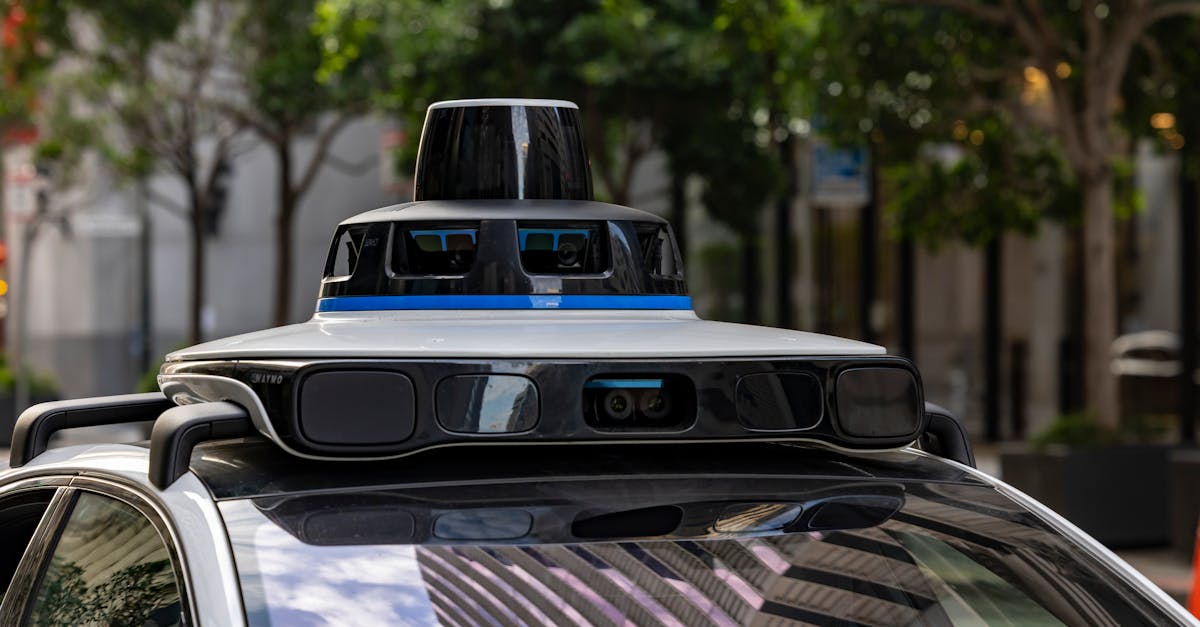 Baidu Apollo Go autonomous robotaxi driving on city street — Photo by Stephen Leonardi on Pexels
2. Apollo Go: From Capital Sink to Unit-Economics Proof
The most glaring gap in BIDU’s current market capitalization is the zero-dollar valuation essentially assigned to Apollo Go.
Two years ago, skeptics routinely cited autonomous ride-hailing as a perpetual cash incinerator. That critique held merit when sensor suites cost tens of thousands of dollars per vehicle and safety supervisors sat behind every steering wheel. Today, Apollo Go operates an active commercial fleet exceeding 12,000 fully driverless units across Wuhan, Chongqing, Shenzhen, and suburban Beijing.
Crucially, the deployment of Baidu’s sixth-generation autonomous vehicle—the RT6—slashed vehicle bill-of-materials costs by more than 55% compared to prior generations. In Wuhan, where operational density is highest, Apollo Go surpassed 220,000 fully driverless weekly passenger trips last month. Unit economics per vehicle have turned cash-flow positive after factoring in amortized manufacturing, remote teleoperation monitoring, and charging logistics.
As local authorities expand operating zones across interconnected municipal borders, municipal transport as a service is graduating from a laboratory curiosity into an infrastructure asset. As investors examine the broader maturation of autonomous transit within future tech portfolios, Apollo Go represents the world’s largest operational test case of autonomous fleet density achieving positive operational margins ahead of Western peers.
3. Ernie Enterprise: Monetizing AI Beyond the Consumer Chatbot
While public attention often fixates on consumer-facing generative chat interfaces, Baidu’s real monetization engine is the enterprise layer of its Ernie platform. Rather than fighting an expensive battle for consumer entertainment attention, Baidu pivoted its cloud division toward mission-critical business deployments.
Over 65% of China’s state-owned enterprises and large private conglomerates now route internal automation workflows through Baidu AI Cloud. Ernie 4.5 and the newly deployed Ernie 5.0 parameter suites are not merely answering text queries; they are powering automated code verification, financial contract analysis, industrial supply chain routing, and pharmaceutical molecular simulation.
Enterprise AI Revenue Composition (Q3 2026 Run-Rate):
-
- Model Training & Fine-Tuning Infrastructure (28%)
-
- API Call Volumes & Token Consumption (41%)
-
- Custom Vertical Application Suites (22%)
-
- Legacy AI Cloud Hosting & Edge Deployments (9%)
This structural shift transforms Baidu’s earnings quality. Search advertising is inherently cyclical, vulnerable to domestic consumer confidence swings and regulatory shifts in verticals like real estate and e-commerce. Enterprise cloud infrastructure contracts, by contrast, carry multi-year renewal commitments and high switching costs.
For enterprise leaders evaluating enterprise platform integration and deployment, tracking the commercial velocity of ai models has become just as essential as monitoring operating cash flows. Baidu Cloud is no longer an also-ran behind Alibaba Cloud and Huawei; in generative AI enterprise workloads, it holds undisputed domestic platform leadership.
4. The Geopolitical Moat and the Silicon Ceiling
Any rigorous forecast of Baidu’s equity trajectory must reckon with the ongoing semiconductor friction between Washington and Beijing. Continued trade restrictions administered through the Bureau of Industry and Security have strictly curtailed access to leading-edge western hardware accelerators, limiting the importation of high-end GPUs.

Yet this constraint has produced an unintended side effect: it engineered an insurmountable competitive moat around Baidu inside its home market.
Recognizing its vulnerability early, Baidu accelerated the development of its proprietary Kunlun AI processor series. Kunlun III silicon, combined with proprietary software compiler optimizations across the PaddlePaddle framework, now handles over 70% of Baidu’s daily inference workloads and an increasing percentage of domain-specific model fine-tuning.
While frontier research requiring tens of thousands of synchronized leading-edge chips remains constrained across the broader domestic industry, Baidu’s software-hardware co-design allows it to achieve higher inference throughput per watt than domestic rivals relying on fragmented, third-party domestic accelerators. Foreign hyperscalers cannot legally offer cloud AI services within mainland borders, leaving Baidu in a near-monopolistic position to capture sovereign enterprise computing spend.
5. Valuation Framework: Value Trap or Asymmetric Buy?
To understand how skewed Baidu’s market pricing has become, institutional investors frequently deploy a sum-of-the-parts (SOTP) valuation framework. Stripping away the consolidated top-line noise reveals an asymmetric balance sheet setup that offers significant downside protection.
As detailed in financial records aggregated on Wikipedia’s Baidu Corporate Profile, the company has consistently maintained one of the most liquid, cash-rich balance sheets in the global technology sector:
- Net Cash and Short-Term Investments: Approximately $26.5 billion in liquid assets and short-term debt equivalents, translating to roughly $76 per ADR in sheer cash value.
- Core Search and Ad Business: Generating reliable operating cash flow, conservatively valued at 5x trailing earnings ($22 billion enterprise value).
- Baidu AI Cloud: Operating at a $4.8 billion annualized run-rate, valued at a conservative 3x enterprise sales ($14.4 billion).
- Apollo Go & Autonomous Tech: Valued conservatively against global autonomous peers at roughly $10 billion.
- Strategic Stakes (iQIYI, Trip.com, miscellaneous investments): Valued at approximately $3.5 billion in market value.
Sum-of-the-Parts (SOTP) Implied ADR Value:
Net Cash & Equivalents per ADR: $76.00 Core Advertising Franchise per ADR: $63.00 Baidu AI Cloud Enterprise Value per ADR: $41.00 Apollo Go Autonomous Fleet Equity per ADR: $28.50 Public Equity Holdings & Investments per ADR: $10.00
Gross Asset Value: $218.50 Consolidated Conglomerate Holding Discount (30%): -$65.55
Net Implied Fair Value per ADR: $152.95 Current Market Price (October 2026): $95.20
Even after applying an aggressive 30% conglomerate holding discount to account for geopolitical friction and regulatory risk, the intrinsic value lands comfortably above $150 per share. The market is effectively pricing Baidu’s high-growth initiatives—Apollo Go, Kunlun hardware, and Ernie Enterprise—at negative value, assuming the core search business collapses overnight.
For portfolio managers balancing risk across global biz it allocations, this dynamic creates an asymmetric setup: the downside is heavily buffered by cash reserves and consistent share repurchases, while the upside requires only a modest reassessment of Baidu’s enterprise cloud growth.
The Verdict: Positioning for BIDU Heading into 2027
The persistent discount applied to Baidu stock throughout 2025 and 2026 has been less about operating fundamentals and more about sovereign asset allocation mandates. Western institutional capital broadly reduced exposure to Chinese equities, sweeping high-quality cash-generative technology leaders into the same defensive exit queue as overleveraged property developers.
That indiscriminate selling has created an unsustainable valuation anomaly.
Baidu is no longer an aging search engine searching for a second act. It has emerged as a vertically integrated AI utility, operating the planet’s largest commercial robotaxi network while anchoring China’s enterprise machine learning migration. With share repurchases actively retiring equity at historically depressed multiples, management is steadily compounding intrinsic value per share.
For long-term investors capable of looking past geopolitical noise, BIDU represents one of the starkest mispricings in the global technology sector today. When institutional sentiment inevitably turns from macroeconomic anxiety back to unit economics and operating cash flows, the repricing of Baidu will not be gradual—it will be rapid, substantial, and overdue.
Last updated Oct 2, 2026
Newsroom
Reporting and analysis from the InnotechInsider editorial team, covering the technology shaping tomorrow.
Related stories

Salesforce Bets the Farm on Autonomous Agents: Can Benioff Kill the Seat?
Salesforce's latest AI agents handle complex sales pipelines without human oversight, accelerating a brutal industry-wide shift away from per-seat SaaS pricing.

The Streaming Canon Tax: What the Top 100 TV Shows Cost in 2026
Streaming the 21st century’s top 100 television shows in 2026 requires eight services, ad-free surcharges, and $1,680 a year—assuming platforms haven’t purged them.

Nvidia Enlists Global Insurers to Underwrite the AI Capex Boom
Facing ballooning cluster financing and depreciation anxiety, Nvidia is orchestrating a reinsurance safety net to protect the multitrillion-dollar AI build-out.