


Crypto’s Most Boring Asset Is Quietly Running Global Commerce
May 30, 2026, 10:30 AM UTC
Photo by Wolfgang Weiser on Pexels
6 min read
TL;DR Dollar-pegged stablecoins generate zero trading buzz because their price never changes, yet they now clear trillions of dollars in real-world remittances, corporate payroll, and supply chain trade.
Pull up a five-year price chart for Tether (USDT) or Circle’s USD Coin (USDC), and you will find the least exciting visualization in finance: a completely straight horizontal line anchored stubbornly between $0.999 and $1.001. There are no sudden peaks to trigger push notifications, no meme campaigns rallying retail buyers to push the token to new records, and no cable news roundtables dissecting breakout technical patterns.
Yet beneath that deliberate flatline sits the single most operational piece of software the blockchain industry has produced.
While speculative assets continue to dominate retail attention, fiat-pegged stablecoins have quietly decoupled from the trading casino that birthed them. Through the third quarter of 2026, annualized on-chain transaction volume for stablecoins crossed $16 trillion, rivaling credit card networks like Visa and surpassing the internal volume of most tier-one regional clearinghouses.
The mechanism did not succeed because it introduced a novel economic theory. It succeeded because it solved the mundane mechanics of moving value between sovereign jurisdictions when commercial banking networks were closed.
The Utility Gap in Public Blockchains
For more than a decade, the core pitch of public ledger technology was currency replacement: mint an unalterable digital asset, limit its supply, and let the market determine its purchasing power. But merchants cannot price milk in an instrument that loses 8% of its purchasing power over lunch, and international import desks cannot invoice inventory in a token whose volatility outstrips their operating margins.
Instead of replacing the sovereign dollar, engineers ended up digitizing it onto open protocols. Stablecoins wrapped conventional fiat currency into transferable bearer instruments that execute over distributed networks 24 hours a day, seven days a week.
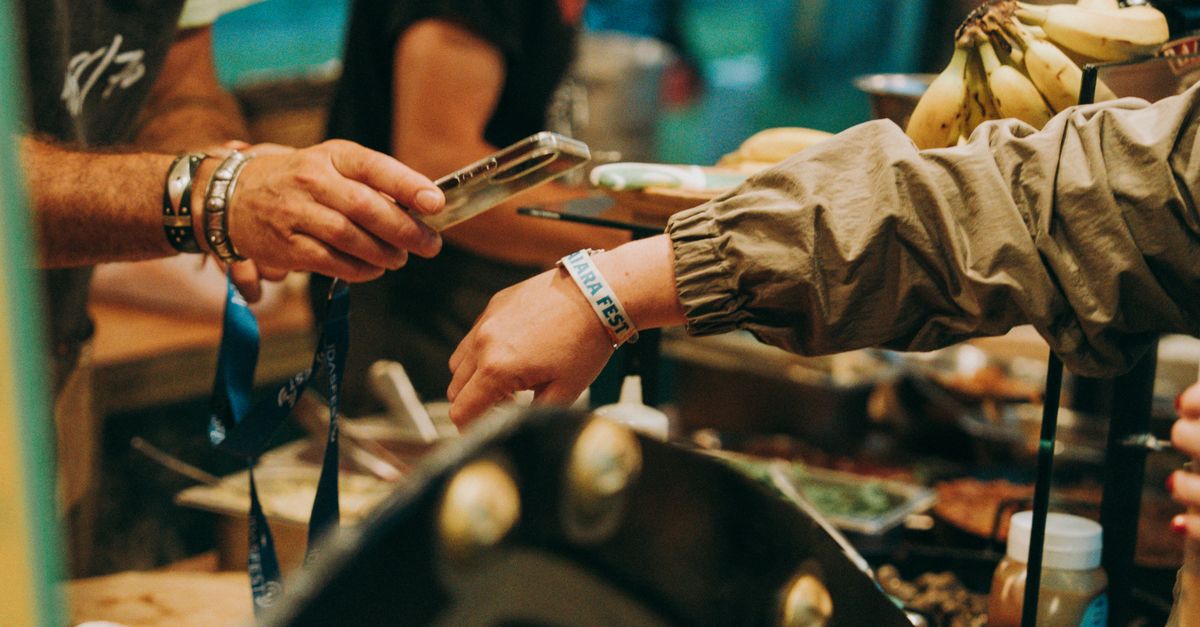 street vendor accepting smartphone payment kigali — Photo by Noland Live on Pexels
The practical consequence has been an exodus away from the legacy correspondent banking architecture. When an enterprise in Singapore needs to settle an invoice with an agricultural supplier in São Paulo, the traditional route requires two domestic clearing systems, three intermediary banks, and three to five business days of trapped capital. By running the payment over modern layer-2 networks, the transfer clears in seconds for a fraction of a cent.
The shift touches everything from contract work to supply chain invoicing, directly intersecting with the broader push across to strip intermediaries out of retail money transmission.
Rail Comparison: Legacy Settlement vs. Modern Stablecoins
The divergence between traditional settlement rails and dollar tokens becomes glaring when broken down by speed, operational hours, and intermediate friction:
| Network / Rail | Primary Asset | Settlement Time | Operational Hours | Intermediary Fees (Cross-Border) |
|---|---|---|---|---|
| SWIFT / Correspondent | Foreign Exchange / USD | 1–4 Business Days | Banking Hours Only (M–F) | $25–$65 + FX spread |
| Fedwire | Central Bank Reserves | Minutes | 21.5 hours / weekdays | $10–$30 domestic only |
| Credit Card Rails | Fiat Currency | Immediate auth, 48h settlement | 24/7/365 | 1.5%–3.5% merchant discount |
| Stablecoins (Layer-2) | Tokenized USD | Under 5 seconds | 24/7/365 | Less than $0.05 network fee |
Traditional wire protocols rely on trusted ledgers reconciling in batches during coordinated office hours. When the Federal Reserve operates Fedwire or national clearers process payments, counterparty risk is minimized by restricting access to regulated depository institutions. Stablecoins run on public software: anyone with an internet connection can hold, verify, and transmit the balance without a specialized corporate charter.
Moving From Grey-Market Trade to Corporate Treasuries
In their early days, stablecoins existed almost entirely to lubricate trading between crypto-exchanges that lacked formal bank accounts. Traders parked their capital in USDT overnight to avoid capital gains events or wire delays.
By 2026, the user demographic has completely inverted.
In regions facing persistent domestic currency depreciation—such as Turkey, Nigeria, and Argentina—stablecoins have effectively become a parallel savings and payments infrastructure. Local freelancers working for European or American clients routinely demand settlement in stablecoins to bypass punitive exchange controls and predatory local banking spreads. For these recipients, having access to dollar purchasing power on an open network is not a philosophical statement about decentralization; it is basic financial self-defense.
 commercial bank treasury trading desk multiple monitors — Photo by AlphaTradeZone on Pexels
Simultaneously, corporate finance departments have stepped into the fold. The high-interest-rate regime sustained over recent years fundamentally altered the underlying economics of token issuers. Reserve managers hold billions of dollars in short-term sovereign debt to back their circulating tokens.
According to analyses published by the Bank for International Settlements, stablecoin issuers have collectively become major holders of three-month United States Treasury bills, competing directly with large hedge funds and foreign central banks for high-grade sovereign paper. This yield dynamic, heavily covered across coverage, gives issuers immense revenue margins that subsidize free or low-cost transactions across public blockchains.
The Regulatory Frameworks Catch Up
The institutional expansion of stablecoins would not have survived the current cycle without structural regulatory clarity.
For years, critics pointed out that unregulated issuers carried reserve composition risks reminiscent of unbacked wildcat banks from the nineteenth century. The implementation of the European Union’s Markets in Crypto-Assets (MiCA) framework, alongside regulatory statutes passed in the United States and the United Kingdom, established strict requirements:
- One-to-one backing strictly restricted to cash and short-dated sovereign paper.
- Mandatory independent, monthly public reserve attestations.
- Segregation of client reserves from issuer operational funds to protect holders against corporate bankruptcy.
- Redemption rights legally codified as par-value direct claims on the issuer.
These guardrails eliminated the risk profile of opaque balance sheets. As systemic uncertainty faded, major payment processors and commercial lenders began integrating stablecoins straight into their merchant checkout flows and B2B software stacks, bypassing proprietary clearinghouses entirely.
The Plumbing Is Complete
Speculative crypto markets will always command social media metrics and televised financial panels. Wild volatility generates immediate drama, fast fortunes, and dramatic losses.
Stablecoins offer none of those spectacles. Their charts will remain flat lines tomorrow, next month, and five years from now.
Instead of overturning the global monetary hierarchy, public blockchain networks ended up accelerating the distribution of the world’s primary reserve asset. The dollar did not get unseated by software; it found a faster set of pipes. The most significant financial upgrade to emerge from the distributed-ledger experiment arrived without price appreciation, masquerading as simple digital infrastructure that simply works when you hit send.
Sources
Last updated Oct 21, 2026
Business & Markets Reporter
Covers startups, venture funding, and crypto markets for InnotechInsider.
Related stories
 Crypto Oct 21, 2026
Crypto Exchanges Brace for Liquidity Shock as Stablecoin Rules Bite
With global stablecoin frameworks hitting enforcement deadlines this autumn, crypto exchange insiders reveal the quiet scramble over liquidity and reserves.
 Crypto Oct 26, 2026
Putting $1,000 Into Crypto's Big Four Five Years Ago: The Math
Placing $1,000 into Bitcoin, Ethereum, Solana, and XRP at the late 2021 peak looked like a ticket to wealth. Five years later, the returns tell a sobering story.
 Crypto Oct 23, 2026
Netanyahu's Crypto Gambit: Preparing for the End of US Military Aid
Facing looming aid expirations and rising sanction pressures, Jerusalem is studying digital asset rails as an insurance policy against Western financial leverage.